Category: Blended Family

Moving to Tennessee in Retirement: Your Complete Estate Planning Guide

Thousands of retirees move to Tennessee every year. Maybe it’s the mountains or being closer to family. Maybe it’s the lower taxes and cost of living. Whatever the reason, there’s one critical aspect of this move that most people overlook until it’s too late: your estate planning documents are still living in your old state.

Those powers of attorney you signed in Illinois? That will you created in California? The trust you set up in New York? They might still be legally valid in Tennessee, but “legally valid” and “practically effective” are two very different things. And some of the planning strategies that worked perfectly in your previous state simply don’t exist in Tennessee.

Here’s what catches most new Tennessee residents off guard: Tennessee doesn’t have transfer-on-death deeds for real estate. If you owned property in Florida, you might have used a ladybird deed to avoid probate. That option doesn’t exist here. If you’re moving from a state with different probate rules, different incapacity planning documents, or different estate planning tools, you need to understand how Tennessee does things and what that means for your family.

This guide walks through everything you need to know about estate planning when retiring to Tennessee, from understanding Tennessee’s specific requirements to knowing which documents need immediate updating and which planning strategies work best in this state.

Why Your Old Estate Plan Might Not Work in Tennessee

When you move to Tennessee from another state, your estate planning documents don’t automatically become invalid. A will created in New York is still a legal document. A trust created in California still exists. Powers of attorney from Illinois don’t disappear just because you crossed state lines.

But here’s the problem: estate planning is highly state-specific. Each state has its own laws governing how documents must be executed, what language they should contain, and how they’ll be administered. What worked in your previous state might not work smoothly in Tennessee.

Financial Institutions

Let’s start with the most practical issue: financial institutions in Tennessee are familiar with Tennessee documents. When someone tries to use a financial power of attorney from another state at a Tennessee bank, the bank often hesitates. Financial institutions don’t make it easy to use powers of attorney in the first place—they’re cautious about fraud and protective of their customers’ accounts. When you show up with a document from another state that looks different from what they normally see, you’re giving them another reason to pause or potentially refuse to honor it.

Medical Providers

The same issue applies to healthcare documents. If your family needs to present your living will to a Tennessee hospital, having a document that Tennessee medical providers recognize and have seen many times before makes the process much smoother. An advance care directive from Tennessee looks like what they’re used to dealing with. A healthcare directive from another state might raise questions or require additional verification.

Witness Signatures and Notaries

Beyond the practical considerations, there are legal differences that can significantly impact your estate plan. Tennessee has specific requirements for how documents must be signed and witnessed. In Tennessee, wills require two witnesses, and those witnesses must be “disinterested,” meaning they don’t have any stake in your estate. Tennessee also doesn’t recognize virtual notarizations for estate planning documents—you need to be physically present with a notary to sign these documents.

Real Estate Transfers

The biggest difference for many retirees is how Tennessee handles real estate transfers. Many states offer tools like transfer-on-death deeds or ladybird deeds that allow real estate to pass outside of probate. These are incredibly useful planning tools that can help avoid the time, expense, and public nature of the probate process. Tennessee doesn’t have anything like this. If you own real estate in Tennessee and want to avoid probate, you might consider placing that property in a revocable living trust. There’s no simple deed option that accomplishes the same goal.

This catches many out-of-state retirees off guard. Some states have ladybird deeds (also called enhanced life estate deeds), which are extremely popular in those states. You can transfer your home using a ladybird deed, maintain complete control during your lifetime, and have it pass automatically to your beneficiaries without probate. When these same people move to Tennessee, they discover that tool isn’t available. If they want the same probate avoidance for their Tennessee home, they need a different strategy.

Understanding Tennessee’s Probate Process and Why It Matters

Before you can make informed decisions about your Tennessee estate plan, you need to understand what you’re trying to avoid: the Tennessee probate process.

Probate is the court-supervised process that happens after someone dies. If you only have a will (or if you don’t have any estate planning documents at all), your estate goes through probate. Your family files a petition with the local probate court. The court oversees the process of gathering your assets, paying your debts, and distributing what’s left to your beneficiaries.

In Tennessee, probate takes a minimum of four months due to creditor notification requirements. The state requires a waiting period to give creditors time to come forward with any claims against the estate. Realistically, even for a simple estate, you’re looking at six to twelve months. If there’s any complexity—business interests, out-of-state property, disputes among beneficiaries—the process can easily take twelve to twenty-four months or longer.

The costs add up quickly. You’ll have court filing fees, but the bigger expense is usually attorney fees. Most families need legal help navigating probate, and in Tennessee, you’re looking at anywhere from $1,500 on the absolute lowest end to multiple five figures for straightforward estates. Complex estates, especially those with family conflict, can generate legal fees much higher than that.

Privacy Concerns

There’s another issue many people don’t consider: Tennessee probate is public. Anyone can go to the probate court and pull up your file. They can see:

  • Your will
  • The inventory of your assets—what you owned and how much it was worth
  • Who your beneficiaries are and what each person is receiving

For high-net-worth individuals, this lack of privacy can be a serious concern. There are people who actually monitor probate records to find out who’s inheriting significant assets. It’s uncomfortable to think about, but it happens. Some families prefer to keep their financial affairs private, and probate makes that impossible.

The Tennessee probate process isn’t necessarily worse than other states, but it’s also not something most families want to go through if they can avoid it. Understanding these drawbacks helps you appreciate why certain estate planning tools—particularly trusts—are so valuable for Tennessee residents.

Tennessee’s Advanced Care Directive: Healthcare Planning Done Right

One of the most important documents you’ll need as a Tennessee resident is called an advanced care directive. This is Tennessee’s specific document for healthcare planning, and it’s different from what many other states use.

Tennessee’s advanced care directive combines two critical healthcare planning tools into a single document. Understanding what each part does helps you appreciate why this document is so important.

Healthcare Power of Attorney

The first part is your healthcare power of attorney. This section names the person who can make healthcare decisions for you if you’re so incapacitated that you can’t communicate those decisions yourself. This isn’t about everyday medical choices—you can still tell your doctor you want the blue pill instead of the red one. This is for situations in which you cannot physically or mentally express your wishes. Maybe you’re unconscious, had a severe stroke, or are in the late stages of dementia. In these situations, someone needs legal authority to make healthcare decisions on your behalf.

Without a healthcare power of attorney, your family would have to petition a Tennessee court to start a conservatorship proceeding. They’d have to prove your incapacity in court. It’s expensive, time-consuming, and emotionally draining during an already difficult time. Having this document in place allows your chosen person to step in immediately without court involvement.

Living Will

The second part of Tennessee’s advance care directive is the living will, which addresses end-of-life decisions. Specifically, your wishes regarding life-sustaining treatment if you’re in a terminal condition or permanently unconscious state.

This is perhaps the most important gift you can give your family. Without a living will, your loved ones have to make agonizing decisions about whether to continue life support. They’re already watching you suffer. They’re dealing with their own grief and emotional trauma. And now they have to make a decision about whether to remove life support, never being completely sure if it’s what you would have wanted.

A living will takes that burden off of them. You’ve already made the decision and put it in writing. They’re simply following your clearly stated wishes rather than making the choice. For families who’ve had to make these decisions without guidance, the emotional weight can be crushing. Having a living will in place is an act of love and protection for the people you care about most.

If you’re moving to Tennessee from another state, you might have similar healthcare documents from your previous state. They might still be legally valid. But Tennessee healthcare providers deal with Tennessee advanced care directives every single day. They know exactly what these documents mean and what authority they provide. When medical decisions need to be made quickly, having a document that providers instantly recognize can make a significant difference.

Choosing Your Healthcare Power of Attorney

When choosing who to name as your healthcare power of attorney, consider both location and capability. If you’re new to Tennessee and your closest family members are still in your previous state, that creates a practical challenge. Healthcare decisions often need to be made in person, with full understanding of the medical situation. Having someone local who can be at the hospital, speak with doctors, and fully grasp what’s happening is valuable.

That said, if your most trusted person lives out of state, they can still serve in this role as long as they can travel to Tennessee if needed and stay in communication with medical providers. It’s a balance between who you trust most and who can practically fulfill the responsibilities.

Financial Powers of Attorney and Tennessee Banking

A financial power of attorney is the document that names someone who can handle your financial affairs if you become incapacitated. This person can

  • Access your bank accounts
  • Pay your bills
  • Manage your investments
  • Deal with your insurance
  • Handle other financial matters on your behalf.

Without this document, if you become incapacitated, no one can access your finances. Your spouse can’t go to the bank and withdraw money to pay for your medical care. Adult children can’t access your accounts to pay your mortgage and utilities. The only option would be for your family to petition a Tennessee court for conservatorship, which is expensive and time-consuming.

Here’s where the Tennessee-specific considerations become critical. If you have a financial power of attorney from another state, it might still be legally valid in Tennessee. But when your designated person actually tries to use it at a Tennessee bank or financial institution, they’re likely to encounter resistance.

Banks and credit unions are already cautious about powers of attorney. They worry about elder financial abuse. They’re protective of their customers. They scrutinize these documents carefully. When someone shows up with a power of attorney that looks different from what they normally see—one from Illinois, California, or any other state—it gives them another reason to hesitate or refuse.

Having a Tennessee financial power of attorney that complies with Tennessee law and aligns with what local financial institutions are accustomed to seeing makes the process significantly smoother. When you need to use a power of attorney, it’s usually during a crisis. Your loved one is in the hospital or dealing with serious cognitive decline. The last thing you want is to be arguing with a bank about whether they’ll accept an out-of-state document.

Requirements

Tennessee has specific requirements for how powers of attorney must be executed.

  1. They must be signed
  2. Witnessed by two disinterested witnesses (people who don’t benefit from your estate)
  3. Be notarized

If your old power of attorney doesn’t meet Tennessee’s requirements, updating it should be a priority.

When naming someone for this role, think about who is both trustworthy and capable with financial matters. This doesn’t have to be the same person you name for healthcare decisions. In fact, it’s common to name different people based on their strengths. Maybe one family member is great with medical matters—perhaps they work in healthcare—while another is more financially savvy and better suited to handle banking and investments.

Why Tennessee Residents Need Trusts More Than Many Other States

If you own real estate in Tennessee and you want to avoid probate, you need to understand one critical fact. Tennessee doesn’t offer the simple probate-avoidance tools that many other states provide.

States like Florida, Michigan, Ohio, and several others have what are called transfer-on-death deeds or ladybird deeds (enhanced life estate deeds). These allow you to deed your property so that it automatically transfers to your named beneficiaries when you die, completely avoiding probate. You maintain full control during your lifetime—you can sell the property, mortgage it, or change the beneficiary designation whenever you want. But at death, it passes automatically without any court involvement.

Tennessee doesn’t have this option. For Tennessee residents who own real estate, there are essentially two paths:

  1. The property goes through probate
  2. It’s owned by a trust.

You could own property jointly with right of survivorship, which means when one owner dies, the other automatically becomes sole owner without probate. This works fine for married couples. But it only postpones the probate issue until the second spouse dies. And it doesn’t help single individuals or people who want their property to go to children or other beneficiaries.

Revocable Living Trusts

This is why revocable living trusts are so important for Tennessee residents who own homes or other real estate. A revocable living trust allows you to transfer ownership of your property into the trust during your lifetime. You serve as your own trustee, which means you maintain complete control. Nothing changes in terms of your ability to use the property, sell it, refinance it, or make any other decisions about it. But legally, the trust owns the property.

When you pass away, your successor trustee can immediately transfer the property to your beneficiaries according to your trust instructions—no probate required. In Tennessee, where you don’t have simpler deed-based options, a trust becomes the most effective tool for avoiding probate on real estate.

The trust benefits extend beyond just real estate. A properly funded trust avoids probate for all assets owned by the trust such as:

  • Bank accounts
  • Investment accounts
  • Personal property

This means your family can settle your estate in weeks instead of months or years. They avoid court filing fees and attorney fees. And they maintain privacy since trusts don’t become part of the public record like probated wills do.

For Tennessee retirees, especially those moving from states where they used transfer-on-death deeds or similar tools, understanding this difference is crucial. The planning strategy that worked in your previous state might not be available here, and you need to adjust your approach accordingly.

Tennessee Trust Requirements: Funding and Administration

Creating a trust document is only the first step. The most brilliantly drafted trust in the world won’t help your family if it’s not properly funded. Trust funding means actually transferring ownership of your assets into the trust. This is where many Tennessee estate plans fall apart.

When your estate planning attorney creates your revocable living trust, they’re creating a legal entity that can own property. But creating the trust doesn’t automatically transfer your assets into it. You have to retitle your assets from your individual name into the trust’s name.

Real Estate

For Tennessee real estate, this means executing a new deed. Your attorney can prepare the deed for you, transferring the property from you individually to you as trustee of your trust. But you have to actually record that deed with the appropriate Tennessee county register of deeds office. If you own property in multiple Tennessee counties, you need to record deeds in each county.

Make sure you understand the timing if you’re moving to Tennessee and selling property in your previous state before buying in Tennessee. If you close on your Tennessee home before you’ve created and funded your Tennessee trust, you’ll need to deed the property into the trust after the fact. It’s usually easier to have the trust created first so the Tennessee property can be deeded directly into the trust at closing, but that’s not always practical given moving timelines.

Bank and Investment Accounts

For bank and investment accounts (excluding retirement accounts, which we’ll discuss separately), you’ll need to contact each financial institution and complete its specific forms to retitle. Instead of your account being in “John Smith’s” name, it becomes “John Smith, Trustee of the John Smith Revocable Living Trust.”

Different institutions have different processes. Some make it easy with simple forms. Others have more complex requirements. Some want to see a copy of your entire trust document. Others accept a certificate of trust, a shorter document that proves the trust exists without disclosing all the private details of your beneficiaries and distributions.

Here’s what you absolutely cannot do: you cannot retitle retirement accounts into your trust. IRAs, 401(k)s, 403(b)s, and other qualified retirement accounts have specific tax rules. If you transfer ownership of these accounts into a trust, it triggers immediate taxation on the entire account balance.

Instead, you name beneficiaries directly on retirement accounts. Typically, your spouse is the primary beneficiary, and your trust or your children are contingent beneficiaries, depending on your specific situation and tax planning goals.

The same applies to life insurance policies. You don’t retitle life insurance into your trust (though there are specialized irrevocable life insurance trusts for advanced estate tax planning). Instead, you update the beneficiary designation to name your trust if that’s appropriate for your situation.

Follow Through

The challenge with trust funding is that it requires follow-through. You can’t just sign the trust document and assume you’re done. You have to contact each financial institution, complete their paperwork, and follow up to ensure the retitling happens. Many people create trusts in Tennessee and then never complete the funding process. Years later, when they pass away, their families discover the trust is empty. All the assets are still in the individual’s name, which means they all go through Tennessee probate anyway—exactly what the trust was supposed to prevent.

As a new Tennessee resident, you also need to think about ongoing funding. When you open new Tennessee bank accounts, make sure they’re opened in your trust’s name from the beginning. If you buy additional Tennessee real estate, make sure it’s deeded to your trust. If you receive an inheritance or sell a business, make sure those assets flow into your trust. Estate planning isn’t a one-time event—it requires ongoing attention as your assets change.

Beneficiary Designations: The Most Powerful Estate Planning Tool You Probably Don’t Think About

Here’s something that surprises almost everyone: beneficiary designations on your retirement accounts, life insurance policies, and certain other accounts override everything else in your estate plan. Your will doesn’t matter. Your trust doesn’t matter. The beneficiary designation controls.

This is one of the most important aspects of estate planning, especially in Tennessee, where many retirees are moving with significant retirement account balances. Understanding how beneficiary designations work and keeping them updated can be the difference between your assets going to the people you intend or going to someone you haven’t thought about in decades.

The way property passes in Tennessee after you die depends on how that property is titled. Joint property with right of survivorship passes automatically to the surviving owner. Real estate titled solely in your name goes through probate unless it’s in a trust. But assets with beneficiary designations—retirement accounts, life insurance, bank accounts with payable on death designations, investment accounts with transfer on death designations—all pass directly to whoever is named as beneficiary, regardless of what your will says.

The Importance of Keeping Beneficiaries Updated

This creates major problems when people don’t keep their beneficiary designations up to date. The most common and most devastating scenario happens after divorce. Someone gets divorced, updates their will and trust to remove their ex-spouse, but forgets about the beneficiary designation on their old 401(k) from a previous employer. When they die, that 401(k) goes to the ex-spouse, regardless of what the will says, what the person’s intentions were, or how long ago the divorce happened.

This isn’t theoretical. It happens regularly.

Example

A divorced woman with two children gets sick. Her financial advisor reviews her accounts and mentions that her ex-husband is still listed as the beneficiary on her retirement accounts. She says she’ll change it. But she’s dealing with medical treatment; she’s not feeling well, she’s busy, and she never gets around to filing the paperwork. When she passes away, her ex-husband inherits two million dollars in retirement accounts intended for her children.

Sometimes the ex-spouse does the right thing and gives the money to the children anyway. But they’re not legally required to. And even when intentions are good, it creates complications and potential conflicts.

Primary and Contingent Beneficiaries

For Tennessee retirees, beneficiary designations are also critical tools for probate avoidance. Assets with properly designated beneficiaries pass directly to those beneficiaries without going through the Tennessee probate process. This is why it’s essential to not only name primary beneficiaries but also contingent beneficiaries.

Your primary beneficiary is who receives the asset first. For most married people, that’s their spouse. But what if your spouse passes away before you do? What if you die together in an accident? That’s where contingent beneficiaries become critical. They’re next in line if your primary beneficiary can’t inherit.

For contingent beneficiaries, you need to think carefully about your specific situation. If you have adult children who are financially responsible, you can often list them directly as contingent beneficiaries.

Minor Children

If you have minor children, you don’t want to list them as direct beneficiaries on large accounts. Minors can’t inherit significant sums outright. Someone would have to petition a Tennessee court, and the court would oversee administration of those assets until the children reach adulthood—exactly the kind of court involvement you’re trying to avoid.

Instead, for minor children, you typically name your trust as the contingent beneficiary. Your trust contains detailed instructions about how assets should be managed for your children, at what age they should receive distributions, who will serve as trustee, and how the money can be used for their benefit in the meantime.

The Exception

There’s one important exception: retirement accounts. For retirement accounts specifically, if you have adult children who are responsible, it’s often better to list them directly as contingent beneficiaries rather than listing your trust. This is due to tax implications under the SECURE Act, which dramatically changed the rules for inheriting retirement accounts in 2020.

The SECURE Act implemented what’s called the 10-year rule for most non-spouse beneficiaries. Previously, beneficiaries could “stretch” inherited retirement account distributions over their lifetime, minimizing the tax impact. Now, most beneficiaries must withdraw the entire account balance within 10 years of the original owner’s death.

How this interacts with trusts is complex. If a trust is named as beneficiary, the tax consequences can be significantly worse than if an individual is named directly, depending on how the trust is structured. Trusts have compressed tax brackets—they hit the highest tax rate at around $14,000 of income, whereas individuals don’t hit that rate until much higher income levels.

This is an area where you need both an estate planning attorney and a financial advisor working together. The right answer depends on your specific situation, your account balances, your beneficiaries’ circumstances, and your overall goals. But it’s critical to understand that what made sense before the SECURE Act may no longer apply. Tennessee residents moving from other states should have their beneficiary designations reviewed in light of these rule changes.

Blended Families and Second Marriages in Tennessee

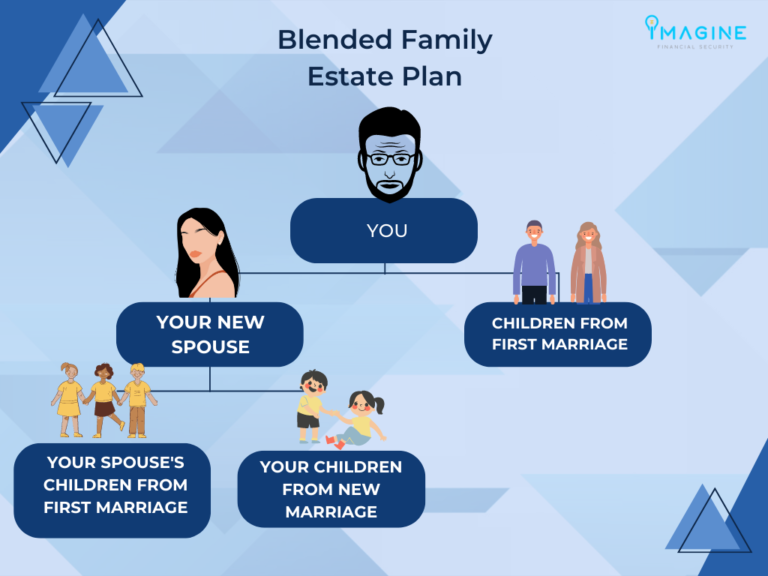
Tennessee sees many retirees in second marriages or with children from previous relationships. These blended family situations require careful estate planning to protect everyone’s interests and prevent future conflict.

The challenge is balancing two important goals: taking care of your current spouse while ensuring your children from your first marriage eventually inherit. A simple will that leaves everything to your spouse creates significant risks. Your spouse could remarry after your death, and your assets could end up going to their new spouse and eventually to that person’s family. Or your surviving spouse might simply decide that since the assets are now theirs, they want to leave everything to their own children from their previous marriage. Without proper planning, your children could end up with nothing.

QTIP Trust

Tennessee trust law offers solutions through specialized trusts designed specifically for blended family situations. The most common is a QTIP trust (Qualified Terminable Interest Property trust). With a QTIP trust, when you pass away, your assets go into a trust that provides income for your spouse during their lifetime. The trust can also make distributions for your spouse’s health, education, maintenance, and support—everything needed to ensure they’re comfortable.

But your spouse doesn’t own the assets outright. They can’t change the beneficiaries. When your spouse eventually passes away, the remaining trust assets go to your children from your first marriage. This structure protects both your spouse and your children.

These arrangements require honest, sometimes uncomfortable conversations. You’re essentially telling your current spouse that you want to make sure your kids from your previous marriage inherit eventually. Some spouses understand and appreciate the clarity. Others might feel hurt or insulted. An experienced Tennessee estate planning attorney can facilitate these discussions and help you find solutions that work for everyone.

Other Complex Situations

Beyond blended families, many Tennessee retirees face another complex situation: adult children with different levels of responsibility or different life circumstances. Maybe you have three children, and two are financially responsible while one struggles with addiction, gambling problems, or simply isn’t good with money.

Tennessee trust law allows you to structure your estate plan so that responsible children inherit their shares outright while the share for the child with challenges remains in trust. A trustee manages that trust share, providing for the child’s health, education, maintenance, and support without giving them direct access to large sums of money that might contribute to their problems.

You can even build incentives into Tennessee trusts. For a child struggling with addiction, the trust could specify that they need to complete treatment, maintain sobriety for a certain period (verified through drug testing), attend a certain number of recovery meetings, or meet other milestones before receiving distributions. The goal isn’t punishment—it’s protection and encouragement for positive change.

The question often comes up: who should serve as trustee for a sibling’s share? This requires careful thought. Naming one sibling as trustee over another sibling’s inheritance can create family tension. One option is to use a corporate trustee—a bank or trust company that serves as a neutral third party. Corporate trustees are experienced, professional, and won’t be swayed by family dynamics. The drawback is the cost and the fact that they don’t know your family personally.

Another option is to name a family member as co-trustee alongside a corporate trustee. This creates a “good cop, bad cop” dynamic in which the family member remains involved in decisions but has the corporate trustee to help enforce boundaries and make difficult calls when needed.

Estate Planning for Single Individuals Retiring to Tennessee

Single people sometimes think estate planning isn’t as important for them. But for single individuals retiring to Tennessee, estate planning is absolutely critical—perhaps even more so than for married couples.

If you don’t have a Tennessee will or trust, Tennessee’s intestacy laws will determine who inherits your assets. These laws try to approximate what a typical person would want, but they often miss the mark for single individuals.

Under Tennessee law, if you’re single with no children and no will, your assets typically go to your parents if they’re living. If your parents have passed away, assets go to your siblings. If you don’t have siblings, it goes to more distant relatives. But what if you’re estranged from your family? What if you’d rather leave your assets to close friends, a long-term partner you’re not married to, or charitable causes you care about? Without proper estate planning documents, your wishes don’t matter—Tennessee’s default plan takes over.

Incapacity Planning

Incapacity planning becomes even more critical for single Tennessee residents. If you’re married, your spouse can often make decisions for you if you become incapacitated (though having formal documents is still important). If you’re single, there’s no automatic decision-maker. Without a financial power of attorney and healthcare power of attorney, your family or friends would have to petition a Tennessee court to start a conservatorship proceeding. They’d have to prove your incapacity in court, which is expensive, time-consuming, and stressful.

Think carefully about who you’d want making decisions for you in Tennessee.

  • A sibling who still lives in your previous state
  • Maybe a close friend here in Tennessee
  • An adult child from a previous relationship

Whoever it is, you need to formally name them in your Tennessee incapacity planning documents. Don’t assume the court will choose the person you would have chosen.

Single individuals also need to think about who will handle their affairs after they pass away. Who will be the executor of your Tennessee will or the successor trustee of your Tennessee trust? This person will need to:

  • Gather your assets
  • Pay your debts and Tennessee taxes (if any)
  • File your final tax returns
  • Distribute your estate according to your wishes

Choose someone organized, responsible, and willing to take on this role. And make sure you have successor options in case your first choice is unable or unwilling to serve.

Tennessee Estate and Inheritance Taxes: The Good News

Here’s one piece of genuinely good news for retirees moving to Tennessee: the state has no estate tax and no inheritance tax. Tennessee eliminated its estate tax in 2016 and had already eliminated its inheritance tax previously.

This makes Tennessee particularly attractive for retirees with significant assets. States like New York, Massachusetts, and several others have state estate taxes with exemption amounts much lower than the federal exemption. If you were planning your estate in one of those states, you might have been implementing sophisticated strategies to minimize state estate tax.

In Tennessee, you don’t have to worry about that. The only estate tax consideration for Tennessee residents is the federal estate tax, and the current federal exemption in 2026 is $15 million per individual ($30 million for a married couple). For most people, federal estate tax isn’t a concern.

That said, these rules are always subject to change.  If you have significant assets that might approach these thresholds, you should be working with an estate planning attorney who stays current on tax law changes and can implement appropriate strategies if needed.

For most Tennessee retirees, though, the lack of state-level estate and inheritance taxes is simply a welcome benefit that makes estate planning more straightforward.

The Tennessee Difference: What You Need to Update Now

If you’re retiring to Tennessee from another state, here’s your action checklist for estate planning documents that need immediate attention:

  1. Advance Care Directive (Healthcare Planning)
    This is Tennessee’s specific document that combines a healthcare power of attorney and a living will. Even if you have similar documents from your previous state, having a Tennessee advanced care directive ensures Tennessee hospitals and medical providers will immediately recognize and honor it.
  2. Financial Power of Attorney
    Get a Tennessee financial power of attorney that follows Tennessee law and meets Tennessee execution requirements. This prevents problems when your designated person tries to use it at Tennessee banks and financial institutions.
  3. Will or Trust
    If you own Tennessee real estate, you need Tennessee-specific estate planning, likely including a trust, since Tennessee doesn’t offer transfer-on-death deeds. Your out-of-state will might still be valid, but having Tennessee documents prepared by a Tennessee attorney ensures compliance with Tennessee law and smooth administration in Tennessee probate courts if needed.
  4. Trust Funding
    If you have a trust from another state, work with a Tennessee attorney to ensure it’s properly funded with your Tennessee assets. This includes deeding Tennessee real estate into the trust and retitling Tennessee bank and investment accounts.
  5. Beneficiary Designations
    Review all beneficiary designations on retirement accounts, life insurance policies, and other accounts. While these don’t need to be “Tennessee-specific,” moving to a new state is a perfect trigger to review and update them. Make sure they align with your current wishes and your overall estate plan.
  6. Digital Asset Planning
    While not Tennessee-specific, make sure your estate plan addresses digital assets, including cryptocurrency, online accounts, and password-protected information. Provide clear instructions about what you want to happen to these assets and ensure your loved ones can access important accounts.

Finding the Right Tennessee Estate Planning Attorney

Not all estate planning attorneys are created equal, and finding the right one makes a significant difference in the quality of your plan and the experience of creating it.

What to Look For

For Tennessee retirees, especially those new to the state, look for an attorney who:

  1. Focuses exclusively on estate planning. Estate planning is complex and constantly evolving. An attorney who dedicates their practice to estate planning stays current on law changes, understands planning nuances, and has deep experience with the issues you’re facing.
  2. Understands Tennessee-specific rules and procedures. Estate planning is highly state-specific. You need an attorney licensed in Tennessee who knows Tennessee probate procedures, Tennessee trust law, Tennessee execution requirements for documents, and how local institutions handle these documents.
  3. Offers both in-person and virtual options. Technology makes estate planning more convenient, but certain steps must be completed in person in Tennessee. Look for an attorney who offers flexibility. Initial consultations and planning discussions can often take place via Zoom, but document signing must be done in person with proper witnesses and notarization.
  4. Has a financial planning background or works closely with financial advisors. Estate planning intersects heavily with financial, tax, and retirement planning. An attorney who understands these connections—or who actively coordinates with your financial advisor—can create a more comprehensive and effective plan.
  5. Takes time to understand your unique situation. Cookie-cutter estate plans created from templates don’t work for most people. Your family situation, assets, goals, and concerns are unique. You need an attorney who asks the right questions, listens to your answers, and creates customized solutions.
  6. Communicates clearly. Estate planning involves legal terminology and complex concepts, but a good attorney can explain things in plain English. You should feel like you understand your documents and the decisions you’re making.

A Note on Online Estate Planning Templates

Online estate planning templates are tempting because they’re cheaper and more convenient. Estate planning is one area where trying to save money up front often ends up costing your family much more in the long run. Tennessee has specific requirements for valid documents. It has unique rules about probate, trust administration, and powers of attorney. An online template created for general use across all states won’t address Tennessee-specific considerations and might not hold up when your family actually needs to use it.

The cost of working with a Tennessee estate planning attorney is an investment in protecting your family and ensuring your wishes are followed. When you consider the potential costs of Tennessee probate, family conflict, or documents that don’t work as intended, professional guidance is worth every penny.

Taking Action: Your Tennessee Estate Planning Next Steps

If you’ve recently moved to Tennessee or you’re planning to retire here, don’t wait to address your estate planning. Here’s what to do right now:

Review Your Current Estate Planning Documents

Read through them. When were they created? What state were you living in? Who did you name in various roles? Are those people still the right choices? Do the documents still reflect your wishes?

Schedule a Review with a Tennessee Estate Planning Attorney

Even if you think your documents are fine, have them reviewed by someone licensed in Tennessee who can identify potential issues and ensure they’ll work smoothly in Tennessee courts and financial institutions.

Review Your Beneficiary Designations

Pull statements for every retirement account, life insurance policy, annuity, and other account with beneficiary options. Check who you’ve named as primary and contingent beneficiaries. Update anything that’s no longer correct.

Verify How Your Tennessee Real Estate Is Titled

Is it in your individual name? Your trust’s name? Jointly with your spouse? Understanding the current title is the first step toward ensuring it’s titled correctly for your goals.

Have the Difficult Conversations

Talk with the people you’ve named as executors, trustees, and powers of attorney. Make sure they’re willing to serve in these roles. Tell them where your important documents are located. Give them your attorney’s contact information.

Create a Comprehensive Asset List

Document all your accounts, insurance policies, real estate, business interests, and other assets. Include account numbers, institutions, and approximate values. Make sure this list includes online accounts and digital assets. Store it securely, but ensure your trusted people know where to find it.

Consider Your Family Dynamics

If you have a blended family, adult children with different circumstances, or other complex situations, don’t try to handle it with simple online forms. Work with an attorney who can create customized solutions.

Plan for Ongoing Review

Put a reminder in your calendar to review your estate plan every three years. Also plan to review whenever you have a major life change—marriage, divorce, birth or adoption of children, death of someone named in your plan, significant change in assets, or health changes.

Estate planning isn’t just about documents—it’s about protecting the people you love and ensuring your wishes are honored. Moving to Tennessee gives you a fresh start and an opportunity to make sure everything is in order. Take advantage of that opportunity.

Legacy is more than what you leave behind. It’s also how you leave it. Taking the time to create a proper Tennessee estate plan, keeping it updated, and making sure it’s properly executed and funded is one of the most important things you can do for your family.

At Imagine Financial Security, we help individuals over 50 with at least $1 million saved navigate these complex retirement decisions. If you are looking to

  • Maximize your retirement spending
  • Minimize your lifetime tax bill
  • Worry less about money

You can start by taking our Retirement Readiness Questionnaire on our website at www.imaginefinancialsecurity.com, so we can learn more about how we can help you on your journey to and through retirement.

Not quite ready to take the questionnaire, but want helpful tips and resources? Sign up for our monthly newsletter and/or subscribe to our YouTube channel.

This is for general education purposes only and should not be considered as tax, legal, or investment advice.

Blended Families – You Need a Long-term Care Plan!

Don't have a Long-term care plan? You are not alone!

Nobody likes to think about the possibility of a family member caring for them later in life.  However, the number one concern I hear from my clients is “I don’t want to be a burden on my children.”  When I ask about how a long-term care event would impact the family, most people have never thought about it.  Or, they’ve thought about it but have yet to create an actual game plan.  

Now, what about long-term care for blended families?  If there are adult children from previous marriages, how does that impact the actual long-term care plan for Mom/Dad?  

In this article, we will dive into the facts about Long-term Care planning, the challenges for blended families, and the top solutions to consider!

The basics

Despite the fact there is a 70% chance you will need long-term care later in life, less than half of retirees over 65 have Long-term Care insurance.  Furthermore, 70% of caregivers are NON paid family members.  So what does this mean?

Even though the probability of needing care is high, people simply ignore long-term care planning.  Or, they simply assume buying insurance is too expensive or they will simply pay out of pocket.  

And despite not wanting to burden their loved ones, they many end up doing just that.  In fact, more than 60% of caregivers have other full time jobs in addition to being the primary caregiver! 

Many people believe Medicare or Medicaid will cover Long-term Care expenses. 

Medicare does not pay for custodial care after 100 days.  Sure, if you are in a rehab facility and expect to improve, you can rely on Medicare to help subsidize those costs for a very short period of time.  Medicaid, on the other hand, does pay for custodial care.  However, most of you will probably not qualify for Medicaid given the financial requirements of income and assets.  And sure, you might assume that your family members will hire help, but the reality is they are NOT hiring help.  Perhaps they believe they can’t afford it, or they are afraid they will burn through assets too quickly and won’t be able to maintain financial independence for themselves.  Both of these are legitimate concerns.

Long-term Care Planning Challenges for Blended Families

Blended families are becoming much more common nowadays.  In fact, 40% of weddings today will form a blended family!  For blended families planning for retirement with adult children, this can provide challenges in three ways:

  1. Who’s assets will be used to pay for long-term care expenses?
  2. How does a long-term care need for your spouse impact your ability to maintain financial independence?
  3. Who’s children will be available to coordinate care?

Who’s assets will be used to pay for long-term care expenses?

which assets to use to pay for long term care

What if you remarried and brought a much larger pool of assets to the marriage than your spouse?  You might have the goal of passing on a financial legacy to your children, but at the same time making sure your spouse is taken care of for life. 

As I discussed in my previous article, 4 Retirement and Estate Planning Strategies for Blended Families, the functionality of a trust for blended families is important.  A trust would allow for you to pass on assets to your spouse, but making sure the next beneficiary is your children once your spouse passes away.

But what if your spouse needs long-term care later in life?  Perhaps they don’t have their own pool of funds to pay for that care.  Inevitably your trust will have to be invaded to pay for those long-term care costs.  The question is, how does this impact your intergenerational wealth planning goals? 

What about your financial independence?

If your spouse needs care and you spent down a large chunk of your assets to pay for it, how does this impact your ability to maintain financial independence after your spouse dies? 

When your spouses passes away, the household will automatically have a reduction in Social Security income.  There could also be a reduction in pension and annuity income, on top of assets being spent down for long-term care.

If you were cruising along and on track to meet your retirement and estate planning goals, how does a long-term care event impact your ability to maintain those goals? 

As we illuded to earlier, most of the time the spouse will care for the other.  Remember, 70% of long-term care is provided by unpaid caregivers.  This means you might forgo hiring professional help in efforts to save your financial resources, but this could negatively impact your mental and physical health.  We’ve seen caregivers get sick after their spouse passes away, simply because they took on the lion’s share of caregiving and are flat out worn out.


Who’s children will be available to coordinate care?

blended family finances

This is the most difficult part of the equation.  Sure you might have enough resources to pay for care.  But, like Jean Ausman shared in our retirement readiness checklist, “a checkbook is not a long-term care plan.”

Who is going to manage the care?

Who is physically going to provide the care?  What if that person is a stepchild? 

Who is going to manage the financials and decide which accounts to tap into for care?

These are all touchy subjects, especially with a blended family where the adult child handling these issues isn’t the biological child of the one needing care.

What is a Long-term Care Plan?

As I discussed in a previous article, Long-term Care Planning, I mentioned the fact that 40% of retirement aged clients have long-term care insurance.  If you read that article, you understand that I am agnostic as to what the solution is, but we need to have a plan.  

These are some questions to get you started:

  • Where will care be provided?  If care is provided at home, you will likely have family providing the bulk of the care.  On top of this, you might hire some professional help to give relief for the family members.  If you need specialized care in a nursing home or memory care, the price tag goes up substantially.  Check out Genworth’s stats on this below.

 
  • What assets will be used to pay for care?  Different accounts will have different tax consequences.  Additionally, certain accounts are better to spend during your lifetime instead of leaving to your children.  Make sure you designate which accounts (in order) should be spent down first if there is a long-term care need.  Take a look at our article on how to divide assets in a blended family.
  • What’s the strategy to mitigate the tax impact of accelerated withdrawals? You might have multiple accounts to draw from, and accelerated withdrawals on certain accounts like 401ks or IRA’s might push you into a higher tax bracket.  Additionally, it could result in higher Medicare premiums as a result of “IRMAA” (income related monthly adjustment amount).  Therefore, you might work with a fiduciary financial planner who also does tax planning to ensure you are making tax efficient withdrawals.  
  • Who is the caregiver coordinator? This job can feel like a full time job, even if the individual isn’t the one providing the care.  The ongoing hiring, firing, financing, and other issues can result in major headaches for the coordinator.  For blended families, what if that coordinator isn’t your biological child?  Or, what if your biological child is the coordinator for your new spouse (their step parent)?  These are touchy issues and can cause a divide amongst the family.  It’s very important to be proactive with all of the children on who is responsible for what.   You also might consider hosting a family meeting so all of the children are on the same page.
  • Who is going to manage the assets? If you plan to hire professionals to provide the care, some additional asset management will need to be considered.  Which investments are being sold when?  How does selling those investments impact the long term viability of the portfolio?  What’s the tax consequence of selling an investment to pay for care?  How does selling an asset impact your legacy goals?  

For traditional families with shared estate planning goals, it can be perfectly acceptable to “self-insure,” as long as the plan is laid out for the decision makers. 

With blended families, particularly those with separate estate planning goals, I highly recommend Long-term Care Insurance. 

The potential challenges for the adult children and your spouse are endless depending on the relationship dynamics, and insurance removes them from the equation (for the most part).  

The benefits of Long-term Care Insurance for Blended Families

  1. Caregiver Coordinator benefit

Immediately after a triggering event, a Long-term Care policy will most likely have a caregiver coordinator benefit.  This allows for the client to call the carrier, and request a specialist to come out to the home.  This specialist will help create a plan to provide care within the framework of the insurance policy’s terms and budget.  Additionally, they can help make recommendations on home modifications to suit the needs of the family.  From there, if there is additional care needed, the family will then decide if they will pay out of pocket or coordinate efforts to provide care.  Nonetheless, the family will have an objective third party to help them with these major decisions.


  1. A long-term care benefit pool

Some policies provide for reimbursement, some provide cash benefits immediately upon the triggering event.  Either way, there is a defined pool of dollars that are specifically meant for long-term care needs.  In addition, the payouts are income tax free, which will eliminate unnecessary tax increases from accelerated retirement account withdrawals.   Why do you think ultra high net worth individuals own Long-term Care Insurance?  Of course they could “self insure,” but they would rather keep their long term investments on their balance sheet instead of liquidating them for care.  

The best part is, having a defined pool of assets will eliminate the question of “do I hire help or provide care myself?”  Instead of putting your spouse or adult children at risk of carrying the weight of caregiving, the insurance essentially forces the family to hire professional help.  You can’t put a price tag on preventing that burden.


  1. Hybrid policies

Over the years, I’ve had clients bring up the concern of “what if I never need care?”  Statistically speaking, there’s a good chance you’ll need care.  In fact Genworth estimates 70% of those 65 or older will need care at some point in life.  But the question is valid.  What if you don’t?  

Hybrid policies were designed to address this issue.  The gist is there is a life insurance benefit with a long-term care benefit.  Some policies are life insurance focused with a long-term care rider.  Others are long-term care focused with life insurance rider.  Either way, if long-term care is not needed.  Or, if only a portion of the benefit pool is used, there will be a death benefit when you pass away that can be left to your beneficiaries.  These policies are certainly more expensive, but you get what you pay for.  What’s also nice is all of the policies I am familiar with are guaranteed to not increase in premiums.  This has been another pain point for the long-term care industry and these policies were also designed to eliminate that concern. 

For those that are interested in leaving a financial legacy to their children, these hybrid policies are a great solution!

Final thoughts

All in all, if you are a blended family with adult children, you must absolutely have a long-term care plan.  If you are similar to a traditional family in the sense of having shared estate planning goals, long-term care insurance might be optional for you.  However, the tax benefits and having a dedicated plan for care makes insurance extremely appealing for all families. 

For blended families with different estate planning goals, long-term care insurance is the top solution!  It’s important to consult with a fiduciary financial advisor that specializes in retirement planning and specifically long-term care planning to create a plan that’s right for you.  An objective third party who can review your goals and balance sheet is invaluable.

If you are interested in discussing your long-term care plan, feel free to start with a no obligation Zoom call with us! (see the link below)

Make sure to subscribe to our blog and join our Facebook group to get the latest retirement planning insights delivered to you!

How to divide assets in a blended family

Benjamin Franklin said “the only two certainties in life are death and taxes.” 

As a fiduciary financial advisor, one of the most important topics to address is how to divide assets in a blended family.

If something were to happen to you, how do things play out?  How do you divide an estate with step children?  How do you protect your assets from stepchildren?   What about the effects of an unequal inheritance?  What about estate planning for a blended family with adult children? 

Each situation is unique.  Take what applies to you, and make a plan!

How to divide your estate with stepchildren?

The reality is that blended families are almost as common as a traditional family.  A blended family is a marriage that involves children from a previous marriage or relationship. 

It’s important to consider your own family dynamics when dealing with retirement and estate planning issues.

A remarriage when children are young is very different than becoming a blended family when the children are adults. 

You might think if the children are young, it’s more likely you will handle your estate planning and wealth transfer strategies like your “traditional family.”  And that may be correct in the sense that you want to divide your assets equally to your biological children and stepchildren. 

One potential hurdle to look out for is guardianship issues of your minor children.  If something unexpected happened to you and your spouse, it’s possible that an ex-spouse might have guardianship rights over your child or stepchild.  Additionally, if your children are minors, the guardian will take custody of their assets until they are age of majority. 

You probably want to avoid your ex spouse taking custody over your children’s inheritance.  Instead, consider setting up a trust and naming a successor trustee (someone other than your ex of course). 

How to protect assets from stepchildren

The most basic form of an estate plan is a will.  A will allows you to name specific beneficiaries that will inherit your assets when you die (among other important decisions).  You could name your spouse, children from your previous marriage, and even perhaps your stepchildren.  You can also exclude anyone you wish within certain limitations.

The issue with having a basic will is that if you do predecease your spouse, all of the assets you leave to your new spouse will be his/her property outright.  This means that after his/her death, the remaining estate will be property of their beneficiaries, likely their children (your stepchildren). 

This could be problematic if your ultimate goal was to leave your remaining estate to your children, not your stepchildren.

The way to get around this issue is to set up some sort of marital trust, the most common being a Marital Bypass Trust.  This can allow you to name the trust as beneficiary of your assets.  The trust could be the beneficiary of all, or a portion of your estate. 

First and foremost, this type of trust will ensure your spouse is taken care of for their lifetime.

Once your spouse passes away, the remaining trust proceeds will then be left to your children (or other remaining designated beneficiaries).  This will prevent any other “unwanted beneficiaries” from receiving your estate. 

If you have an existing trust, make sure it’s been reviewed and updated in accordance with the SECURE Act rules.  Otherwise, there could be some unfavorable tax consequences for your beneficiaries.

blended family estate planning

What about adult children in a blended family?

If you are a blended family with adult children, it’s possible one or more of the following might apply:

  • An age gap with your new spouse
  • You or your spouse have accumulated substantial assets before your remarriage
  • You and your new spouse might have children together and separately
  • Your new spouse might be closer in age to your adult children

If there is an age gap in the remarriage, it’s likely that you will have two separate estate planning and wealth transfer strategies.

  1. Take care of your spouse for their lifetime
  2. Leave a financial legacy to your children

As discussed earlier, the likely solution here is to set up a trust that allows for your spouse to benefit, and then ultimately your children.

However, you may consider leaving some or all of your assets to your adult children if:

  • your spouse is financially independent
  • you don’t want your children to wait until your spouse dies to receive their inheritance

If this is appealing, you must be aware of the elective share rules in your state.

Elective Share

For community property states, assets accumulated jointly are assumed to be owned by both parties.  However, in non-community property states you can own assets separately despite being married.  You can leave those assets to another beneficiary other than your spouse, as long as you leave your spouse a certain % of your total estate (this is known as the Elective Share).

Florida, for example, has an Elective Share rule stating 30% of your assets must be left to your spouse, regardless of what your estate plan says.  Additionally, there is no requirement for how long that new marriage lasted! 

Even if you set up a trust, certain trusts might fail the elective share test.  Therefore, be careful if you have goals to leave a larger portion of your estate to your children instead of your spouse.  

If you and your spouse are financially independent, you might consider signing a prenup or a postnup.   This will ensure that you have the legal right to “disinherit” your spouse and overrides the elective share rules.

Consider Life Insurance

Life Insurance is a great tool if you have multiple estate planning and wealth transfer goals.

Here’s an example: 

Let’s say the bulk of your assets are inside of a 401k or IRA and you get remarried. 

Let’s say your adult children are on their own, building their careers and growing their families.  

Because of this, you’d like to leave your kids money when you die, but you also want to make sure your new spouse is taken care of during retirement.

First, you may consider setting up a trust for the benefit of your spouse and naming that trust the beneficiary of your 401k or IRA.  Your children would be the contingent beneficiary of the new trust.   This will protect against any stepchildren or new spouses from inheriting your assets.

If the trust is set up properly, your spouse can maintain favorable life expectancy rules when it comes to required minimum distributions.

Now that your spouse is covered, you buy a new life insurance policy with your children as primary beneficiaries.  This way, they aren’t waiting for stepmom/stepdad to pass away to receive their inheritance.  If you already have life insurance, you could make sure it’s structured properly and simply name your children as primary beneficiaries.

This also gets around the issue of the elective share.  The calculation for the elective share will typically not include death benefits from life insurance.  However, it might count cash value, so make sure you structure the policy properly in accordance with your state’s rules.

If the goal is to own the policy throughout retirement, you will want to make sure it’s a permanent policy, not term.  Term insurance is more likely to expire before it pays the death claim, and you don’t want to be shopping for permanent insurance when you’re 70.

blended family with adult children cooking

Effects of an unequal inheritance

If you have multiple sets of beneficiaries, you might be thinking of the effects of an unequal inheritance. 

Let’s say you have adult children that are well off financially.  However, you also have children with your new spouse that are still 100% dependents. 

In this scenario, you might consider leaving a larger percentage of your estate to the side of the family that needs it most. 

If you consider this strategy, I highly recommend setting up a trust.  This will reduce the likelihood of issues being contested in court, and the terms of the trust remain private.  Additionally, it’s likely your dependent children are minors and would need someone to oversee their inheritance (a trustee) until they are responsible adults.

Another consideration for an unequal inheritance is the impact of income sources that will be lost for the surviving spouse.  This could include Social Security, pensions, annuities, distributions from IRA’s and investment accounts.

Upon the first spouse passing away, the surviving spouse is entitled to the larger of the two Social Security benefits.  However, this still results in a reduction of Social Security income for the survivor. 

If you have a pension or annuity that stops at your death, you also need to consider the impact of this lost income.

If your IRAs or 401ks are left to your children instead of your spouse, could your surviving spouse maintain their standard of living for years or even decades to come? 

Additionally, would your surviving spouse be able to pay for long-term care if a large portion of your estate was left to your children? 

These are all issues you should think through to help divide your assets within your blended family. 

One final thought on this topic is that it’s not just about how much you leave, but how you are remembered.

The act of making things easy to manage for your loved ones is a big part of how you will be remembered!  Leaving a big mess to clean up won’t help that cause, regardless of how much money you leave behind.

Tax Considerations

consider taxes for estate planning

The types of assets that are left to children, your spouse or a trust are all important from a tax standpoint.

Qualified Retirement Accounts

Leaving your qualified retirement accounts to your spouse outright will create the optimal tax benefits.   These include IRAs, 401ks, 403bs, 457bs, TSPs etc.

On the other hand, leaving qualified assets to your children will likely trigger the new 10-year rule.  With the SECURE Act coming into effect in 2019, these accounts can no longer be stretched according to the child’s life expectancy.  This will likely result in an acceleration of taxes that could have been minimized had these accounts been left to a spouse.

Naming a trust as beneficiary of a qualified plan also presents some challenges.  Tax brackets are significantly higher for trusts versus an individual. 

In 2022, a Married Filing Joint taxpayer would have to earn over $647,850 in taxable income to cross the highest tax bracket at 37%. 

For trusts, the highest tax bracket threshold is only $13,450! 

If you name a trust as beneficiary of a retirement plan, make sure your attorney has revised or drafted the documents to align with the SECURE Act rules.   This could mitigate unnecessary tax implications.

Taxable Investments

Investments including stocks, bonds, mutual funds, ETFs, real estate, tangible property and even crypto assets would fall under this category.   This assumes these investments are held outside of an IRA, 401k or other qualified retirement plan. 

The major tax benefit for these assets is the step up in cost basis after death.

How does the step up in cost basis rule work?

Let’s say you bought $100k of Apple in 2000 and it’s now worth $500k.  If you sold $500k worth of Apple, your capital gain would be $400k (500k – 100k). 

If you die before selling it, your beneficiary gets a “step up in the cost basis.”  Instead of your beneficiary paying taxes on the gain of $400k, their new cost basis is now $500k.  If they sold the stock immediately thereafter, they would have little to no capital gains taxes due!

For married couples, there are some additional rules that are based upon the state you live in.  For community property states, assets are assumed to be owned jointly, and therefore only ½ of the basis is assumed to be stepped up upon the death of the first owner.  Upon the death of the second owner, than the full step up rule is applied. 

In non-community property states, you could in fact own assets separately from your spouse so they can take advantage of the FULL step up at your death.  This could be accomplished with a revocable living trust in your name only, OR perhaps individual ownership with your spouse as beneficiary (via TOD or POD designations). 

Make sure you consider your estate planning and wealth transfer goals before making any changes to your asset titling!

Life Insurance

We’ve already discussed the functionality of leveraging life insurance to take care of one or more of your wealth transfer objectives.

From a tax standpoint, this is one of the most tax efficient assets to leave a beneficiary.  It’s 100% income tax free and probate free!  Additionally, you can structure this strategy to pass outside of your estate by way of an Irrevocable Life Insurance Trust (ILIT). 

If you have a beneficiary with special needs, you could also fund their “Special Needs Trust” with life insurance. 

Action Items

Your estate planning and wealth transfer strategies should be personal to you!

Make sure you are taking care of your loved ones the way you intend to. 

Make sure you have the proper documents in place that align with your intentions.

Make sure you update and revise all of your beneficiary designations.

Make sure your financial plan is coordinated with your estate plan and wealth transfer goals.

And finally, do your best to make things simple for your loved ones.  Communication and clarity are critical to avoid unnecessary conflict.  You don’t want your loved ones to question “why” things were set up a certain way.

I hope you found this information valuable!

Make sure to SUBSCRIBE so you don’t miss out on any of our retirement planning insights!

SCHEDULE A ZOOM call if you want to discuss your current situation with a Fiduciary.

And finally, join our “BLENDED FAMILY RETIREMENT AND ESTATE PLANNING” Facebook group for ongoing dialogue and insights from our team of experts!

4 Retirement and Estate Planning Strategies for Blended Families in Florida

What is a blended family and why does it impact my retirement plan?

First, what is a blended family?

Simply put, a blended family involves a remarriage that comes with children from a previous marriage or relationship.  Maybe you and your new spouse both have children from previous marriages.  Or, perhaps you have children with an ex and a current spouse. 

There are many varieties of blended families, and they are quite common.  In fact, it is estimated that 40% of households with children in the United States are blended of some kind.  Each blended family has unique circumstances, but retirement and estate planning strategies are more complex when it comes to dealing with blended families.  I have been working with blended family retirement planning for over 13 years in our home base of Florida, as well as across the United States virtually, so let’s discuss some key issues to focus on.

How does having a blended family impact my retirement plan?

There are four major topics we will cover in this post.  Keep in mind, there are other considerations you should address, and no two families are identical.  You have to consider your own family dynamics, financial situation, and much more.  However, this should get you started as you think about planning for retirement with a blended family.

  1. When should you claim Social Security?
  2. How will you approach your retirement income withdrawal strategies?
  3. How will you pay for Long-term care costs?
  4. Inter-generational Wealth Planning and Estate Planning
retirement planning for blended families

1. When should you claim Social Security?

Social Security is likely your largest source of guaranteed income in retirement.  It represents 40% of all income for those 65 and older.

There is a possibility you and your spouse each have children you may want to leave assets to, and this could impact the surviving spouse’s retirement income plan.  For example, if you have three children and a new spouse, you may decide to divide your estate into 1/4 for each beneficiary. 

However, Social Security is one income stream that will always be available to the surviving spouse, no matter what.  So, how can you maximize the lifetime benefits for you and your spouse?

If you and your spouse are both eligible for Social Security benefits, the surviving spouse will keep the larger benefit after the first spouse dies.  If you have the opportunity to delay Social Security longer to maximize your benefit, this will also maximize your surviving spouse’s benefit if they were to outlive you.  If you are able to delay until age 70, you will be eligible for your largest monthly benefit.  If that benefit is larger than your spouse’s, it will help maximize their Social Security income in the event some of your assets were not left outright to your spouse.


Other blended family Social Security nuances....

Dependent benefits are also important. 

22% of men and 18% of women have a 10 or more year age gap in a second or third marriage.   Therefore, you may have remarried a younger spouse, with potentially dependent children.  Or, you are remarried and had new children with your younger spouse.  Nonetheless, if you are approaching retirement age, consider dependent benefits for Social Security!  Dependents are defined as children under age 18 (or 19 if still in high school), or disabled before 22.  These dependents could be eligible for a Social Security benefit when you start collecting yours!  The benefit is equal to 50% of your primary insurance amount and is available for each dependent child and for your spouse, regardless of age! 

There is a cap on the total amount paid based on your primary insurance amount, and it usually ranges between 150%-180% of your full retirement benefit.  The caveat is you must begin claiming yourself in order to trigger the dependent benefits.  This may result in you filing earlier than you had anticipated.  Therefore, you have to run some calculations to see what is best for your situation.

Another consideration is determining your ability to collect Social Security on an ex-spouse.  This will depend on how long the previous marriage lasted, and whether it ended in a divorce or premature death. 

For example, if your first spouse passed away and you remarried after age 60, you could still qualify for survivor benefits on your former spouse.  On the contrary, if you were remarried before 60, those former spouse’s survivor benefits will be forfeited. 

For divorcees, ex-spousal benefits will be forfeited (in MOST cases) once you are remarried, but you would then be eligible for a spousal benefit from your new spouse.  This is often a consideration on whether or not to legally remarry if your former spouse’s benefit would result in a significantly higher monthly benefit.  But let’s be honest, if you want to marry your new partner, don’t let a few extra Social Security dollars prevent you from doing so!  

2. What is a safe withdrawal strategy for retirement income?

There is a good chance you and your new spouse both had assets before you were remarried.  Perhaps you and your spouse have Traditional IRAs, 401ks, Roth IRAs, and taxable brokerage accounts.  However, those account values probably vary between the two of you.  Furthermore, you may have slightly different estate planning goals involving children from your previous marriages. 

The key is to come up with a safe withdrawal strategy from each bucket based on:

  • tax characteristics
  • risk tolerance
  • inter-generational wealth planning or estate planning goals
  • insurance coverage
  • other income sources like Social Security or a pension

If you plan to leave everything to your new spouse and simply divide it evenly between all of the remaining children, the withdrawal strategy is more straightforward.  However, if your children will inherit assets upon your death, how does that impact your new spouse’s retirement income plan?  Will they have enough to live on throughout their life expectancy?  Remember, Social Security will be reduced after the death of the first spouse, as discussed earlier. 

Also, let’s say each of you has children from a previous marriage.  If you are burning through your assets more aggressively to support the retirement lifestyle, how does that impact your goal to leave money to your children? 

safe withdrawal strategies for blended families

The SECURE Act changed the game with inherited IRA's/401k's.

If your children are in a higher tax bracket, you might not want to leave them your IRA or 401k outright.  Your surviving spouse will likely have more favorable withdrawal options and be able to stretch this account over their life expectancy.  Conversely, leaving the 401k or IRA to your children will likely trigger the new 10-year rule from the SECURE Act of 2019.  This would force them to liquidate the retirement accounts fully within 10 years, likely triggering a much higher tax consequence than had you left those assets to your spouse.  This is especially true if you are a Florida resident without a state income tax, and your children are residents of a state with high-income taxes (California, New York etc.).  In these situations, you may want to consider a slightly higher withdrawal rate on your 401ks or IRAs, and a slightly lower withdrawal rate on your taxable brokerage accounts or Roth accounts.  This way, you maximize the tax friendly assets to your children, and also maintain the tax efficiency of traditional 401ks and IRAs by leaving them to your spouse first. 

There is no one-size-fits-all solution to creating a withdrawal strategy, but starting with open conversations about each other’s legacy goals for both sets of children and getting on the same page about a plan is a great first step.  Once the goals are set, a safe withdrawal rate should be established.  I wrote an article about this and you can read it here.  The basic formula I use is; Financial Goals – Income sources  – Risk Intolerance = Safe Withdrawal Rate from investments.  Noticed how I used risk intolerance instead of risk tolerance.  The reason is that the less risk you are willing to tolerate (the higher your intolerance score), the lower your withdrawal rate would be to accommodate for lower expected investment returns.


Should I follow the 4% rule?

Bill Bengen created the 4% rule back in the 1990’s, which back tested rolling 30 year retirement periods from 1926 to 1976.   He concluded that a 4% withdrawal rate resulted in money left over at the end of retirement in all of the tested periods.   You could certainly use this as a starting point, but there is much more to consider.  If you want to maximize the inheritance for your children, you might need to stay close to 4% or even below it!  If you don’t have a huge desire to maximize your estate to children, you might be able to inch closer to a 5% or even 6% safe withdrawal rate. 

If you are comfortable with more volatility in your investments in order to maximize returns, you could potentially have a slightly higher withdrawal rate than 4%, perhaps 5%-6%.  On the other hand, if you cannot withstand any volatility, supporting a 3%-4% withdrawal rate is a more realistic goal. 

Finally, guaranteed income sources play a role in determining your rate of withdrawal.  If you have most of your expenses covered by Social Security and/or a Pension, your rate of withdrawal required might even be 0%!  In this scenario, you could choose to simply reinvest your earnings, gift to your children or even your favorite charity.  On the other hand, if guaranteed income is a very small portion of your required standard of living, your rate of withdrawal might be higher than average.

All of these factors; guaranteed income, risk intolerance, and financial goals; play a role in determining what withdrawal rate to use, so be careful with using a rule of thumb from a textbook.

Using the "Guardrail" approach to withdrawals...

The higher your withdrawal rate, the greater the uncertainty.  If you are more aggressive with your investments, you could expect higher returns, and maybe for a period of time a 5% or even 6% rate of withdrawal works just fine.  However, what happens when the first recession hits?  Or the first bear market?  

This is why we like to use Dynamic Withdrawals by way of a “Guardrail Approach.”  This involves reducing the rate of withdrawal during a significant downturn in stocks.  Conversely, our clients can increase spending when markets are performing well.  In our modeling, we have concluded that this is the best way to maximize the safe withdrawal rate, but at the same time maintain flexibility based on current economic conditions.  I also wrote more in-depth about this topic in this blog post.

Should I Buy An Annuity?

One final topic to consider is whether or not you will purchase an annuity to fund retirement.  There are many flavors of annuities, but the general concept is to create an income stream that you cannot outlive, much like Social Security.  These products also provide some peace of mind in that the income stream is typically guaranteed, and not tied to market volatility.  If you don’t have a pension, this could be a nice supplement to Social Security.  Furthermore, you can name your spouse as a joint annuitant to ensure that they will continue to receive the life income if they outlive you. These products can also be beneficial in that it could allow you to take more risk with your investment portfolio, as well as impact your safe withdrawal rate, knowing that a good portion of your expenses will be covered by guaranteed income.  

Many consumers believe they will be sacrificing their intergenerational wealth planning goals for their children or grandchildren by purchasing an annuity.  Based on research in the industry, this might be true if you were to die prematurely.  However, if you were to live to or past your life expectancy, it could actually result in an increased amount of wealth transferred.  The reason is because your investments were able to ride the ups and downs of the market without being tapped into during a recession or bear market.  I always recommend seeing what’s out there and comparing the rates between several carriers as they do vary greatly. 

Finally, interest rates have been on the rise so far in 2022, and that trend is expected to continue at the moment.  Therefore, the payout rates have become quite attractive for new annuitants, so it’s prudent to do some due diligence as you approach retirement.

3. Long-term care planning

Concerned woman reviewing documents at laptop

Long-term care planning is complicated enough to prepare for during retirement.  For blended families, long-term care planning is even more complex. If you and your spouse both accumulated assets for retirement, how will one pay for Long-term care costs if they are needed?  Do both of you have Long-term care insurance?  Or, do you plan to self insure?  Are your estate planning goals the same?

Chances are, we will all need some level of custodial care at some point in our lives.  The question is, how extensive is the care?  And, for how long is care needed? Genworth published their annual study that indicates there is a 70% probability of needing Long-term care costs for those 65 or older.  If you have children from a previous marriage, and your spouse needs care, are you going to burn through your own assets to pay for it?  If you are like me, you will do anything you can to take care of your spouse and give them the proper care they need.  However, if you have goals to leave money to your children, is that a risk worth NOT planning for? 

On the other hand, if your spouse has children from a previous marriage and you needed care, how would he/she pay for it?  Would you expect your spouse to accelerate withdrawals on their accounts unnecessarily in order to provide you care?

Should I buy Long-term Care Insurance?

If you are still young enough and healthy enough, you could consider buying Long-term care insurance. The last time I checked, it’s very rare to find a company that will cover you if you are over age 75. The sweet spot is often between 50-60 years of age, as there is a much lower decline rate and premiums are still affordable. When you get into your 60s and 70s, the decline rate goes up substantially and your premiums are quite costly.

Long-term Care Insurance is a very clean way to dedicate specific resources for this major retirement risk. Of course, nobody has a crystal ball, and you might be in the 30% that never needs care, but it’s a gamble you may not want to take.

There are also hybrid Long-term Care and Life Insurance policies that will provide a death benefit if you never use the funds for Long-term Care. Or, a reduced death benefit if you only used a portion of the Long-term Care benefit. This can provide you with some peace of mind knowing that someone will benefit from the policy. These products are much more expensive, so be prepared to write some larger checks.  Also, work with a broker that can represent multiple carriers to help you shop around.

What about an annuity with a Long-term Care rider?

If you or your spouse have health issues that might preclude you from getting traditional Long-term Care, consider an annuity with a Long-term Care rider.  These products do require a certain level of funding, but they are a viable option if you have a nest egg you could allocate to protect against this risk.  Even Suze Orman, who is typically anti life insurance, is an advocate for these types of hybrid policies!

What about “self-insuring?”

There is nothing wrong with self-insuring,  just over half of my clients decide to go this route. 

If you decide to self-insure, having that discussion with your spouse about what assets to use to pay for care is critical!

If you have accounts that are more tax favorable to leave to your heirs, you may not want that account aggressively spent down for your care!

Also, consider the state you live in relative to your beneficiaries.  If you live in a state like Florida or Tennessee without a state income tax, you might consider using some of your 401k or IRA to pay for care.  This is especially relevant if your children are in a higher tax bracket and/or live in a state with high income taxes.

Have a plan, communicate it with your spouse, your financial planner, and your other agents so they know what to do!  I also wrote an entire article on Long-term Care planning if you want to check it out here.

4. Estate Planning Basics for Blended Families

We have touched on some of the estate planning and intergenerational wealth planning challenges throughout this article.  Each spouse might bring a slightly different perspective on transferring wealth.  However, the amount you leave or who you leave it to isn’t the only estate planning challenge for blended families.  Here are some other key points to consider:

  • Who will step in to help make financial decisions as you get older?
  • What about healthcare decisions?
  • Who is going to be the executor of your estate, or successor trustee?
  • Do you have any special considerations for any of your beneficiaries? (special needs, spendthrift concerns, son/daughter-in-law concerns, or stepchildren that you may or may not want to include)

These individuals should know what their role is, and what it is not!  We’ve all heard of horror stories when someone dies without a plan, and unfortunately impacts how that person is remembered.  If you have ever watched the show “This is Us,” there is a scene in the last season where Rebecca calls a family meeting with her three adult children and her second husband.  This is a textbook model on how a family meeting should be conducted! 

If there are different sets of children involved, consider naming one child from each “side” to participate.  If it’s a successor trustee role, perhaps you can name successor co-trustees to avoid any ill will. 

I certainly would make sure that a successor trustee or successor financial power of attorney is financially savvy and responsible.  This does make things a bit tricky if one “side” does not have a viable option.  Instead, I’ve seen where families will name the successor trustee a corporation, also known as a corporate trustee, to serve in that capacity.  This way, clients don’t have to worry about anyone’s feelings being hurt because they couldn’t be trusted. 

Don’t worry about giving specific dollar amounts on what you are leaving.  You certainly can, but it’s not the point.  The point is proactive communication and agreement from the adult children and other beneficiaries.  This can really protect their relationships long term, which is far more meaningful than the dollar amounts they each receive.

If you didn’t see the episode of This Is Us, check it out here!

Should you consider a trust for your blended family?

I spoke with my own attorney and friend in detail about this.  His name is Ryan Ludwick and he’s an Estate Planning specialist with Fisher and Tousey law firm based in Florida.  He told me some couples come in with the idea they want to simply leave everything to one another, and then whatever is left will be divided evenly to the children.  This makes things very simple, almost like a traditional family estate plan. 

However, certain blended family dynamics could be solved with a trust.  For example, if you want your spouse to utilize the assets for retirement if they were to outlive you, but still guarantee the remaining assets are left to your children, you might consider a trust.

A trust would essentially be set up for the surviving spouse.  When you pass away, the trust becomes irrevocable (nobody can change it), and your spouse can use the assets for their care.   Once the second spouse dies, the remainder beneficiaries (presumably your children) will receive the trust assets.

A few reasons why a trust could make sense are:

  • The assets held in trust would not be up for grabs in the case of a remarriage.
  • Potential creditor protection benefits.
  • Oversight – meaning you could name a trustee to help manage the trust, in case your surviving spouse was incapacitated down the road, or if they don’t have the financial acumen.
  • And of course, the terms are your terms, and cannot be altered.
Ryan also made a great point to be careful with naming a trust as primary beneficiary of a retirement account (401k or IRA).  There might be unfavorable tax results by doing so, and you should consult with your financial planner and estate attorney before making any changes. 
 

Life Insurance

Life Insurance could also be a great tool for estate planning for blended families.  You could set up a new policy, or change the beneficiary of an old policy, to satisfy certain estate planning goals. 

For example, let’s you wanted to split your investment assets four ways at your death between children and your new spouse.  Between your spouse losing one Social Security benefit and only receiving 25% of your estate, their ability to maintain financial independence could be at risk.  Therefore, you could consider leaving your life insurance policy to your spouse to make them whole. 

On the other hand, you may not want to leave those 401ks or IRAs to your children for reasons mentioned before.  Therefore, you could elect to leave those assets to your spouse (outright or in a trust), and leave the life insurance policy to your children.  The death benefit is always tax free, so this solves the issues related to inheriting retirement accounts with the new SECURE Act law. 

Elective Share Rules

Ryan said to “be careful of the elective share rule for spouses.”  In Florida, and many other states without community property laws, the spouse is entitled to a percentage of the estate, regardless of what your will says.  For Florida, it’s 30%.  So let’s say you only designate 10% to your spouse in your will, he or she could contest this in court, and would likely win. 

There are legal ways to get around this by way of signing a prenuptial agreement, or having your spouse sign a waiver form.  It’s just something to be mindful for, especially with blended family estate planning.

Final word

As you can see, blended families are unique in an of themselves, so cookie cutter retirement and estate planning advice doesn’t work.

There are other considerations for blended family retirement planning, and no two situations are created the equal, which is why we love helping people like you!

Book a call with us!

If you have questions or want to discuss your situation, feel free to book a 30 minute Zoom call and we would be happy to connect with you. 

Subscribe to our email list!

If you liked this article, be sure to subscribe to our email list so you don’t miss out on any of our latest articles!